What changed on April 1, 2026
The Florida Office of Insurance Regulation adopted a new version of the Uniform Mitigation Verification Inspection Form, OIR-B1-1802 (Rev. 04/26). Any inspection done on or after April 1, 2026 has to be on it.
- Two new questions: your home's wind region, and its roof slope.
- More detail on the roof covering and roof deck, including spray foam.
- FORTIFIED roofs: a FORTIFIED Roof, Silver or Gold certificate can now count as proof for several answers.
- Secondary water resistance now lists the methods that qualify. Regular roofing felt doesn't count.
The 9 questions on the form
| # | Question | What it looks at |
|---|---|---|
| 1 | Building code | When the home was permitted. In Miami-Dade, homes built under the South Florida Building Code after the 1994 changes can qualify. |
| 2 | Region (new) | Your wind zone. All of Miami-Dade, including Homestead, is in the High-Velocity Hurricane Zone (HVHZ). |
| 3 | Roof slope (new) | Whether the main roof is 6 in 12 or steeper, or flatter than that. |
| 4 | Roof covering | The roof type and its product approval. |
| 5 | Roof deck attachment | The nails or screws holding the roof sheathing down. |
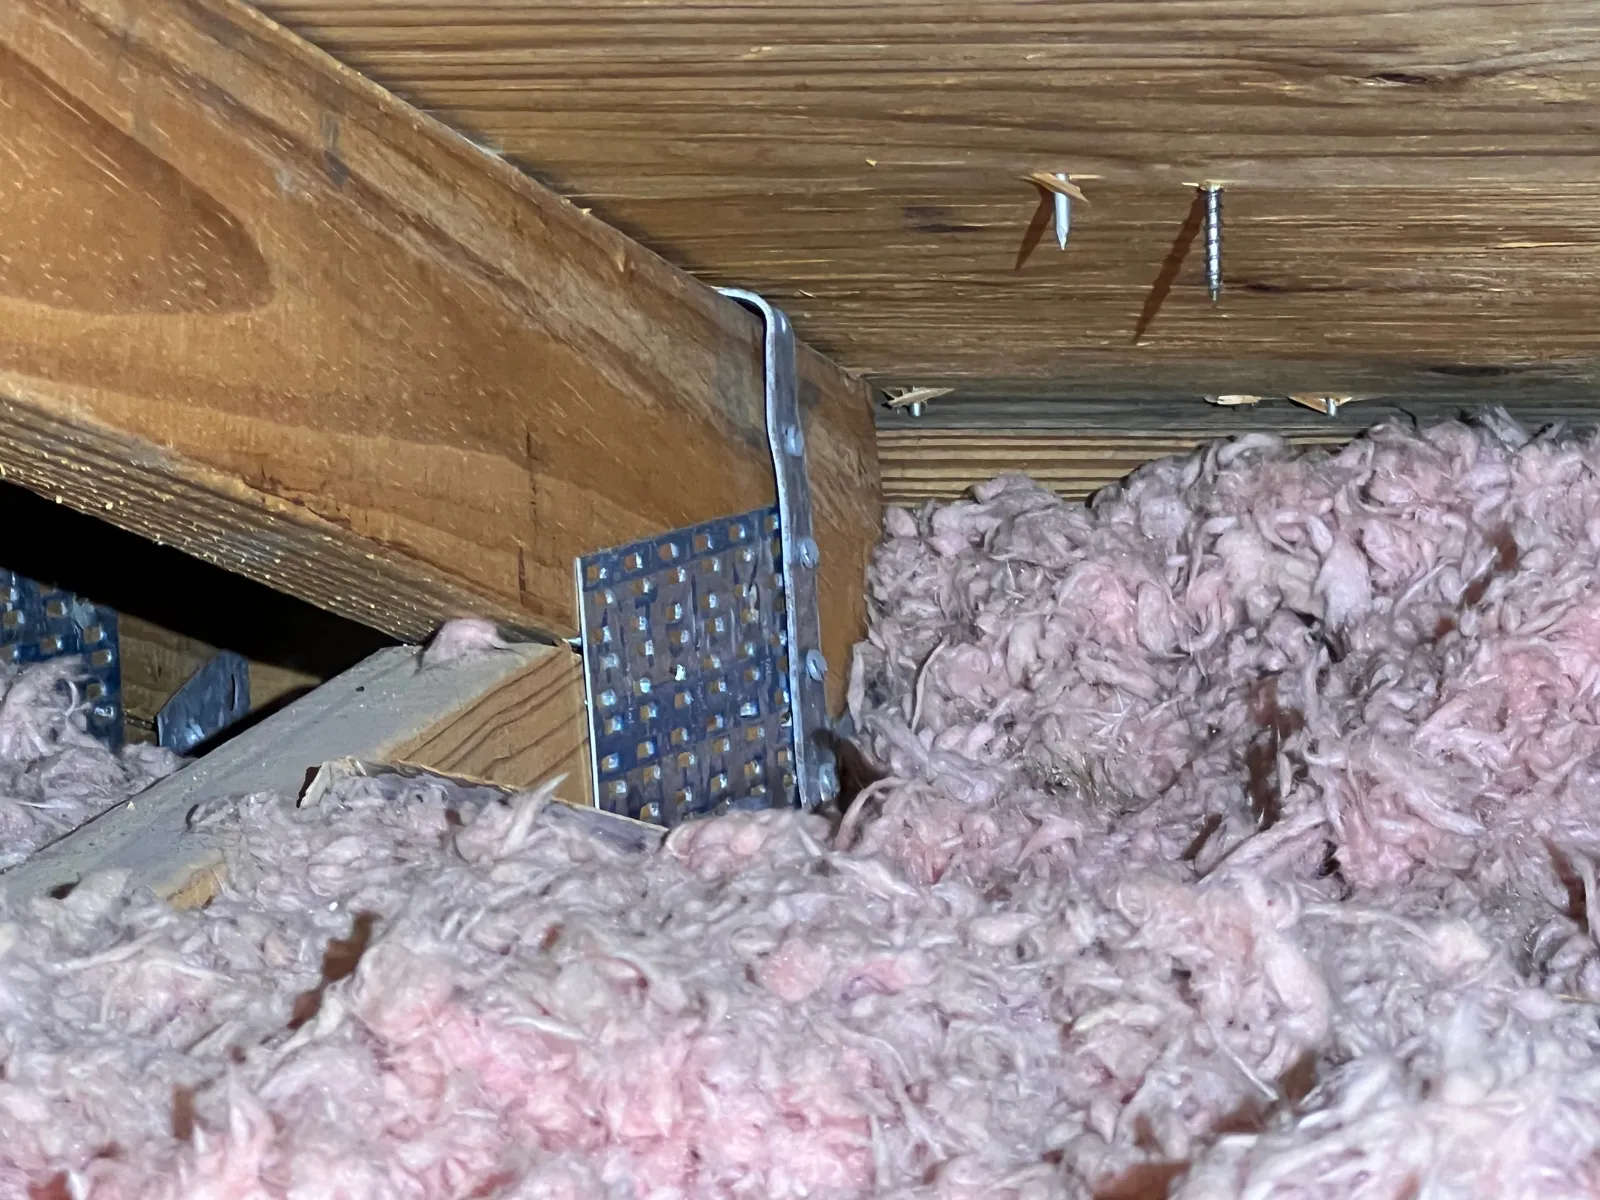
| 6 | Roof-to-wall attachment | Toe nails, clips, single wraps or double wraps. |
| 7 | Roof geometry | Hip, flat or other (like gable). |
| 8 | Secondary water resistance | A sealed layer under the roof covering. |
| 9 | Opening protection | Impact windows, doors, skylights, garage door and shutters. |
Is my old wind mit still good?
A wind mitigation form is valid for up to 5 years, as long as nothing on the house has changed and nothing on the form is wrong.
For the older form (Rev. 01/12), Citizens says it still accepts one done within the 5 years before April 1, 2026, if the house hasn't changed. An older-form inspection done after March 31, 2026 isn't valid. Other insurers set their own rules, so ask yours.
If you replaced the roof, windows or garage door since your last one, get a new inspection. Those changes can earn you more credit.
How it can lower your premium
Florida law (s. 627.0629) requires insurers to give reasonable discounts for features that reduce wind damage, and to post their discounts on their websites. The discount only applies to the hurricane-wind part of your premium.
Florida's own notice to homeowners says securing the roof and protecting your windows are the two most cost-effective upgrades. How much you save depends on your insurer and your house, so I won't promise a number. What I can promise is that every feature your house really has ends up on the form, with a photo behind it.
Who can sign it
Under s. 627.711, the form can be signed by a licensed home inspector who has completed hurricane mitigation training, a building code inspector, a general, building or residential contractor, an engineer, or an architect. Home inspectors have to do the inspection in person.
I'm a Florida licensed home inspector (HI18810) and I do every inspection myself.
The free option: My Safe Florida Home
The state's My Safe Florida Home program offers free wind mitigation inspections for owner-occupied, homesteaded single-family homes. Grants to pay for upgrades have more rules: generally a home built before 2008, an insured value of $700,000 or less, and low or moderate income.
Funding can run out, so check mysafeflhome.com. If your insurer gave you a deadline, call me and you'll usually have the report this week.
Sources
- Florida OIR: wind mitigation resources
- Florida OIR: form OIR-B1-1802 (Rev. 04/26)
- Citizens: wind mitigation form changes (March 2026)
- Florida Statutes s. 627.0629: wind discounts
- Florida OIR: mitigation discount notice (OIR-B1-1655)
- Florida Statutes s. 215.5586: My Safe Florida Home
- My Safe Florida Home: funding status
This guide explains the rules in plain words. It is not legal or insurance advice. Ask your insurance agent what your policy needs.